Exterminator insurance for an independent operator comes down to a short list of lines: general liability, applicator pollution liability, commercial auto, workers compensation once anyone else works with you, and professional liability if you inspect or write reports. State licensing sets a minimum, and your customers’ contracts set the number you actually need.
The lines independents carry, in the order they usually need them
General liability. This is the first policy any customer or property manager asks for. It answers injury and property damage on the job: a customer slips on a treated floor, a tech damages a fixture, a ladder goes through a window.
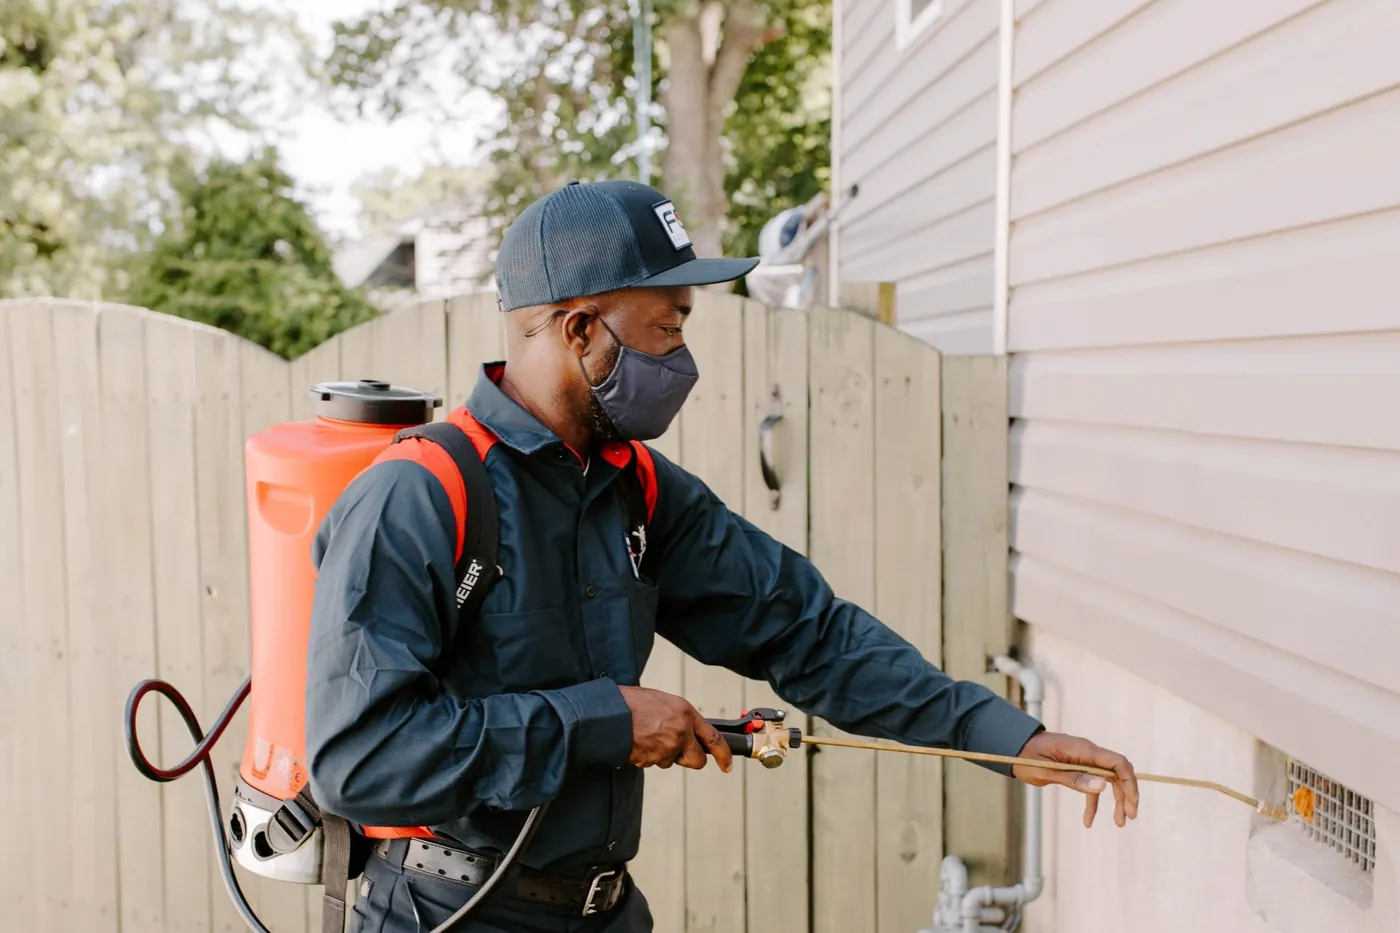
Applicator pollution liability. The standard general liability form excludes chemical release, and chemical release is the central risk of your work. Drift, overspray and misapplication belong here. For an independent operator this is the line most often missing, because the license filing can be met without it.
Commercial auto. Your truck carries product, tanks and tools and spends more hours on the road than on any one property. Personal auto forms commonly limit business use, and the post on whether you need commercial auto for pest control trucks explains why the trade is rated as a business vehicle.
Workers compensation. If you work alone, the question is often whether your state requires it for an owner. The moment someone works with you, it is a different question, covered below.
Professional liability. If you inspect for wood-destroying organisms, write reports, or give written recommendations and guarantees, a missed finding or a failed treatment can create a financial loss that general liability does not answer. The post on a missed termite inspection walks that claim.
What state minimums look like, and what they leave out
State minimums are a good illustration of why they are a starting point. These are required limits for licensing, taken from each state’s own text, not amounts anyone suggests buying:
- Arizona requires proof of financial security of at least $500,000 for a pest management business license, and liability insurance is one of the ways to post it (A.R.S. 3-3615).
- Colorado requires liability insurance of at least $400,000 for a commercial applicator business license, and says a policy containing a pollution exclusion still satisfies it (C.R.S. 35-10-106).
- Virginia sets $100,000 for property damage, $100,000 for personal injury to or death of one person, and $300,000 per occurrence for a licensed pesticide business (Va. Code 3.2-3927).
- California requires $500,000 for bodily injury to any one person and $500,000 for property damage for a registered structural pest control company (Structural Pest Control Act, 8692).
Read what those requirements leave out. Colorado’s accepts a policy that excludes pollution. Virginia’s says the required financial responsibility need not apply to damages or injury to agricultural crops, plants or property being worked upon by the applicant (Va. Code 3.2-3927), which means the statute does not even require protection for the property you are treating. Those are licensing rules written to give the public a source of payment, and they are not a design for your protection.
Exterminator insurance for independent operators: the structure question
Many independents start as a sole proprietor and ask whether an LLC changes the insurance picture. An entity can separate some personal assets from business liabilities, but it does not replace insurance, and a claim against you personally for your own negligence follows you whatever the entity. The post on an LLC versus a sole proprietorship in pest control covers the decision, and the post on starting a pest control business puts insurance in its place in the startup sequence.
Where you store product matters as well. Chemicals kept in a garage or a home shop create a fire and contamination exposure that a personal residence policy generally does not treat as business property, and the post on stored pesticides and chemicals in a fire explains how that claim runs.
Your tools, your truck and your equipment
Sprayers, bait stations, pumps and the rig on the truck are the capital of a small operation, and a theft or a roll-over can end a season. Contractors tools and equipment coverage is written for equipment that moves between jobs and sits in a vehicle, which a property policy on a building does not follow.
The first helper changes everything
The moment someone works beside you, the program changes. A helper can be hurt by chemicals, a ladder or the road, and workers compensation is built for that. Some states require licensed pest control companies to file a certificate of workers compensation with the licensing board unless the company files a statement that it has no employees. California’s Act is one example (Structural Pest Control Act, 8693).
Whether a helper is an employee or an independent contractor is a legal classification, not a label you choose, and the answer drives workers compensation, licensing and liability. Get advice before the first hire. Licensing can also bite: in California, for example, the Board’s licensing page states that applicators and field representatives work for a registered company and do not contract for pest control work on their own behalf (Board licensing page).
Deductibles and who pays them
A small operation pays its own deductible out of cash it needs for payroll and product, so a high deductible chosen to save on the policy can turn a modest claim into a cash problem. Some regulators police this directly. Arizona caps the deductible at one percent of the required financial security per occurrence and requires other security for any excess (A.R.S. 3-3615). Even where no statute applies, pick the deductible you could pay on the worst week of the year without missing a payroll.
Working as a subcontractor to another pest control company
Many independents take overflow work, specialty treatments or route coverage from a larger company. The prime contractor will usually ask you to carry its required limits, name it as an additional insured, and sign an indemnity that makes you answer for your own work. Read those terms before the first job. An indemnity you assumed by contract can be excluded under a policy that only covers liability you would have had anyway, and the prime’s requirements may exceed anything your license asks. Treat the subcontract as an insurance document and send it to your agent before you sign.
The slow season is not a reason to drop coverage
Independents in seasonal markets sometimes cancel policies in the winter to save cash and rewrite them in spring. Problems follow. A lapse in coverage is a gap in the claims-made policies that most professional liability programs use, and work completed before the gap can lose its protection. And any customer relationship that outlasts the season, including a prevention contract or a warranty, keeps its exposure whether or not a policy is in force. Ask your agent about installments and a lower exposure basis in the off months before you let a policy lapse.
Certificates, subcontractors and what customers ask for
Customers rarely ask what your license requires. They ask for a certificate of insurance, often with additional insured status and a waiver of subrogation. A property manager hiring an independent wants to know the limits, the cancellation terms and whether pollution coverage applies. The post on winning commercial pest control contracts covers how those requirements arrive. If you subcontract part of a job, require the same from them, because their lapse becomes your claim.
Real-World Scenario. An independent operator runs a one-truck route from a pickup. A customer’s property manager asks for a certificate, and the operator provides a general liability policy that meets the state minimum. Months later a treatment drifts onto a neighboring yard. The liability policy carries a pollution exclusion, the personal auto policy is irrelevant to a drift claim, and no pollution policy was bought. The operator’s license is in good standing and the claim is the operator’s to pay out of the business and, depending on the entity, out of personal assets.
A short review for small operations
- Confirm general liability, pollution coverage and commercial auto are in force and match the work.
- Ask your agent in writing whether the liability policy excludes pollution.
- Decide how you will staff before the first hire, and get the classification advice you need.
- Insure the equipment and the product storage separately.
- Keep your certificate current and send it before a customer asks.
The general pest control service page covers how route work is underwritten, and the EPA’s FIFRA summary gives the federal frame. To have your program built around a small operation, tell us how you work.